In This Article
The common floor across published requirements is a personal credit score of about 625 to 660, at least 12 months in business, and roughly $100,000 in annual revenue. Online lenders sit at or below that floor; banks sit above it, usually asking for 2 years under the same ownership and a score of 660 to 700 or more. Merchant cash advances go lowest, from a 550 score and 6 months in business.
Quick answer: Credibly (merchant cash advance): 550+, 6 months, $20,000 a month. OnDeck: 625, 1 year, $100,000 a year. Bluevine (line of credit): 625+, 12 months, $10,000 a month. American Express (line of credit): 660+, 12 months, $3,000 a month. Chase (line of credit): 660+, ownership unchanged 2 years, $100,000 a year. Bank of America (unsecured loan): typically above 700, 2 years, $100,000 a year. The SBA publishes no minimum score for 7(a) loans.
Every figure below is quoted from the lender's own website, last checked September 24, 2026. Lenders change their criteria; check before you apply.
Published minimums by lender
| Lender | Product | Credit score | Time in business | Revenue | Also required |
|---|---|---|---|---|---|
| Credibly | Merchant cash advance | 550 or higher | At least 6 months | $20,000+ average monthly revenue | Revenue deposited into a bank account |
| OnDeck | Term loans and lines of credit | 625 personal FICO | 1 year | $100K annual revenue | Business checking account |
| Bluevine | Line of credit | 625+ personal FICO | 12+ months | $10,000 a month ($120,000 a year) | Corporation or LLC; no bankruptcies; good standing with the Secretary of State |
| American Express | Business line of credit | At least 660 (may be higher) | At least 12 months | At least $3,000 average monthly revenue | Applicant 18 or older |
| Wells Fargo | Small business line of credit | Typically at least 680 | Typically at least 6 months in operation | Not published on this page | |
| Chase | Business line of credit | At least 660 | Majority ownership and management unchanged for 2 years | At least $100,000 annual revenue | |
| Bank of America | Unsecured term loan | Above 700 typically required | 2 years under existing ownership | $100,000 prior-year revenue | |
| Crest Capital | Equipment financing | "A solid credit history" (no score published) | Typically 2+ years under current ownership | Not published | |
| SBA 7(a) | Government-backed loan, through a lender | No minimum published; must be "creditworthy" | Must be an operating business | Must be "small under SBA size requirements" | For-profit, located in the US, unable to get the credit on reasonable terms elsewhere |
Read the table as floors, not approvals. Meeting a lender's published minimum means you can apply. It does not mean you will be approved, or for how much.
What the minimums tell you
- The lower the price of the money, the higher the bar. Bank lines and loans ask for 2 years and 660 to 700+. Online lenders ask for a year and about 625. A merchant cash advance asks for 6 months and 550, and usually costs the most.
- Revenue is set in two ways. Banks and OnDeck quote an annual figure, most often $100,000. Bluevine, American Express and Credibly quote a monthly one. $10,000 a month is $120,000 a year.
- Time in business often means time under the same owner. Chase, Bank of America and Crest Capital all count ownership, not only the age of the business.
- The SBA sets rules, not scores. Its page lists who is eligible. The lender that makes the loan sets its own credit threshold.
What lenders check beyond the minimums
Clearing the floor gets an application read. These decide the answer and the amount:
- Cash flow. Most lenders size the loan from what the business can repay each month, commonly leaving a margin of about 1.25 times the payment. Our business loan calculator runs that math.
- Existing debt and advances. Payments you already make reduce what a new loan can be.
- Deposit consistency. Steady months read better than a few big ones.
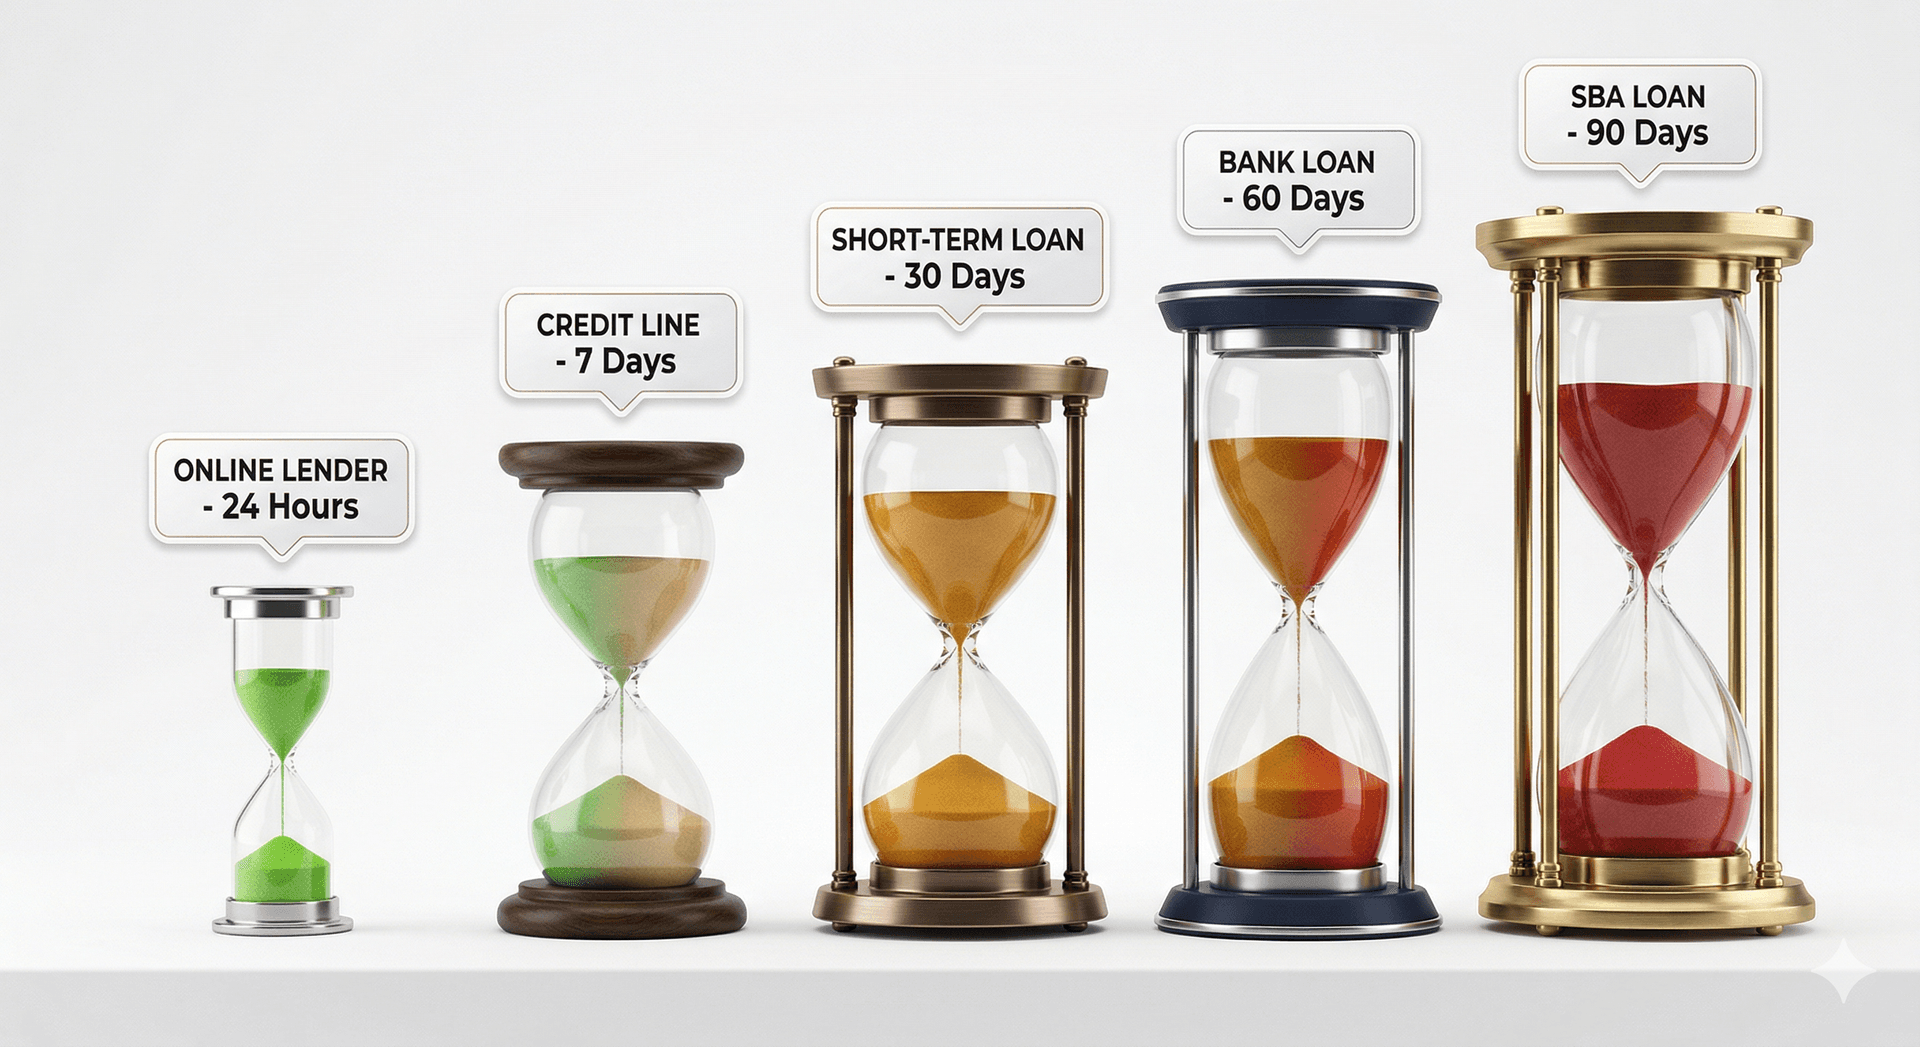
- Bank statements and a full application. A lender decides on a complete file; see approval times by lender.
- Industry and purpose. Some industries are restricted at some lenders, and a defined use of funds underwrites better than an open-ended one.
- A personal guarantee. In the Federal Reserve's 2025 survey, 59% of firms with debt used a personal guarantee to secure it (source).
For more on each factor, see what lenders look for in a business loan application.
Frequently asked questions
What credit score do I need for a business loan?
It depends on the lender and the product. Published minimums on the lenders' own sites run from 550 for a merchant cash advance (Credibly) to 625 at OnDeck and Bluevine, 660 at American Express and Chase, and typically above 700 for a Bank of America unsecured loan.
How long does my business need to be open?
Six months for some merchant cash advances and lines of credit (Credibly; Wells Fargo typically). Twelve months at OnDeck, Bluevine and American Express. Two years under the same ownership at Chase, Bank of America and Crest Capital.
How much revenue do I need?
Published figures range from $3,000 a month (American Express line of credit) to $10,000 a month (Bluevine), $20,000 a month (Credibly) and $100,000 a year (OnDeck, Chase, Bank of America).
Does the SBA have a minimum credit score?
The SBA's 7(a) page does not publish one. It requires the business to be creditworthy and able to repay, and the lender making the loan sets its own threshold.
What do lenders look at besides credit score?
Cash flow, existing debt, how steady your deposits are, your bank statements, your industry and what the money is for. Many also require a personal guarantee.
See which funding partners are ready to fund a business like yours at TopFunders.ai. Free to use, and checking your options doesn't affect your credit.
Sources (read 2026-09-24)
| Lender | Exact wording on the lender's page |
|---|---|
| Credibly | "At least 6 months in business"; "Minimum $20,000 in average monthly revenue"; "A credit score of 550 or higher"; "Revenue deposited into a bank account" |
| OnDeck | Minimum requirements: "1 Year in business", "Business checking account", "$100K business annual revenue", "625 personal FICO score" (the page also lists stronger-odds criteria: 2+ years, 675+, $250K+) |
| Bluevine | "a corporation or LLC in business 12+ months, with no bankruptcies on file, and in good standing with your Secretary of State. Your business must also earn $10,000 in monthly revenue, or $120,000 annually, and you must have a 625+ personal FICO credit score." (their dash between the two revenue figures rendered as a comma) |
| American Express | "Have a FICO score of at least 660 at time of application"; "Have been in business for at least 12 months"; "Have a business representative/applicant who is at least 18 years of age or older"; "Have recent average monthly revenue of at least $3,000"; "The required FICO score may be higher based on your relationship with American Express, credit history, and other factors." |
| Wells Fargo | "Typically, guarantors have a FICO Score of at least 680 at the time of application, and have been in operation for at least 6 months." |
| Chase | "Business annual revenue of at least $100,000"; "FICO Score of at least 660 is required"; "Majority ownership and management have not changed in the past two years" |
| Bank of America | "Minimum 2 years in business under existing ownership. Personal credit above 700 FICO Score is typically required."; "Minimum $100,000 in prior year annual business revenue." |
| Crest Capital | "businesses typically need 2+ years under current ownership, a solid credit history, and a demonstrated ability to make payments" |
| SBA 7(a) | "Be an operating business; Operate for profit; Be located in the U.S.; Be small under SBA size requirements; Not be a type of ineligible business; Not be able to obtain the desired credit on reasonable terms from non-federal, non-state, and non-local government sources; Be creditworthy and demonstrate a reasonable ability to repay the loan" |