In This Article
Industry rarely sets the approval clock on its own. The product you apply for, and how complete your application is, set it. Across the eight industries below, online lines of credit and term loans typically decide within hours to a few days of a full application, equipment financing often the same day, and merchant cash advances within hours, while SBA-backed loans take weeks to months. What slows approval is industry-specific: reimbursement timing in healthcare, lumpy project payments in construction, seasonal income in agriculture.
Quick answer: Healthcare and medical practices: hours to a few days online, weeks to months for SBA-backed practice loans. Restaurants and retail: hours to a few days, driven by card and deposit volume. Trucking: often same-day decisions for equipment financing. Construction, technology and real estate: a few days online, longer when income is lumpy or concentrated in one client. Agriculture: a few days online, longer when income arrives at harvest. The clock starts at a full application with bank statements.
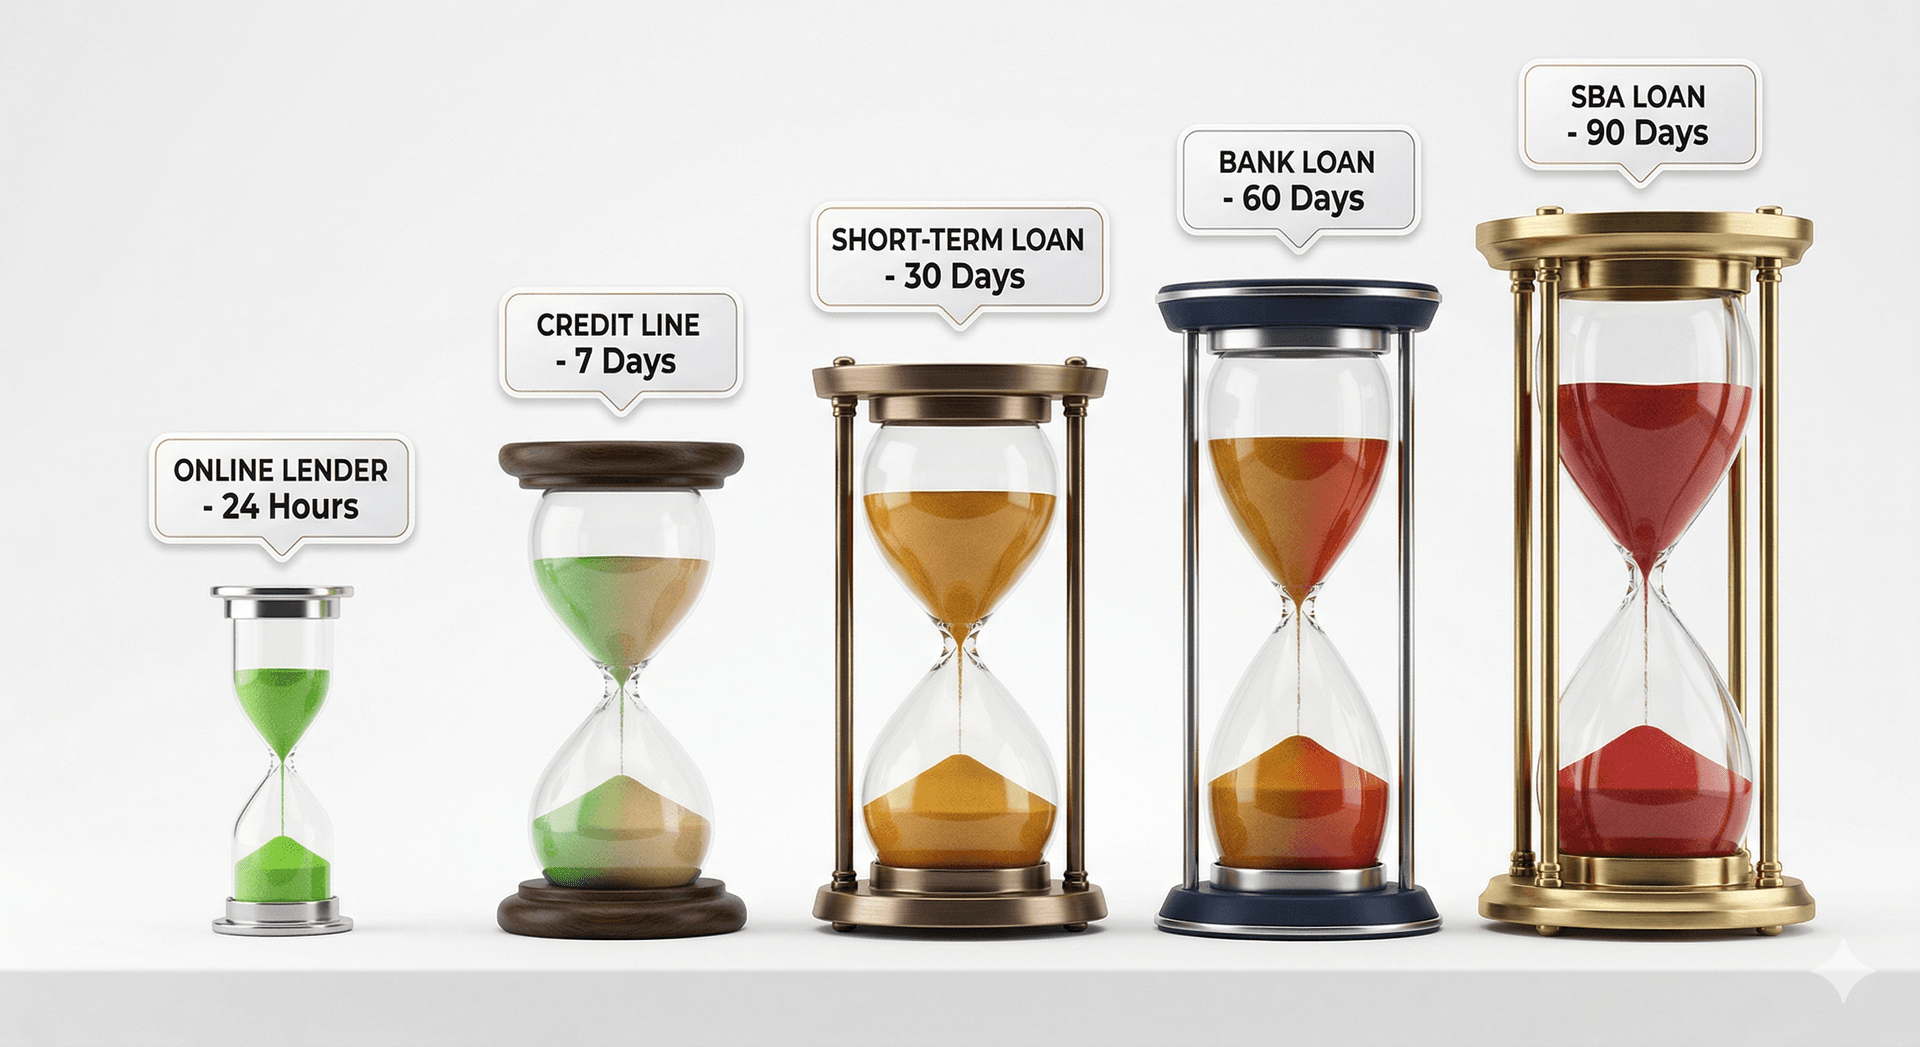
This guide sits beside our approval times by lender type and approval times by product.
Approval times by industry: summary table
| Industry | Typical products | What slows approval | Typical time from full application |
|---|---|---|---|
| Healthcare and medical practices | Term loans, lines of credit, equipment financing, SBA-backed practice loans | Payers reimburse weeks after the work, so collections can look uneven; an expansion without a defined cost | Hours to a few days online; weeks to months SBA-backed |
| Restaurants | Lines of credit, term loans, equipment financing, merchant cash advances | Uneven weeks; existing advances already taking a share of daily takings | Hours to a few days |
| Trucking | Equipment financing, term loans, lines of credit | A new authority; a truck without a vendor quote or resale value | Often same day for equipment financing; a few days otherwise |
| Construction | Term loans, lines of credit, equipment financing | Lumpy project payments; one main contractor as the only customer | A few days online; longer when deposits are lumpy |
| Retail | Lines of credit, term loans, merchant cash advances, equipment financing | Occasional spikes instead of steady daily volume; existing advances | Hours to a few days |
| Real estate | Term loans, lines of credit | Commission spikes instead of recurring fees; an open-ended "capital for growth" ask | A few days online |
| Technology | Term loans, lines of credit | Milestone payments instead of recurring contracts; one client covering most revenue | A few days online |
| Agriculture | Equipment financing, term loans, lines of credit | One harvest payment instead of steady deposits | Often same day for equipment financing; a few days otherwise, longer around harvest |
All times are typical ranges, not promises from any lender. They describe how long a decision usually takes once the lender has a full application, and they vary with the lender, the amount and the file.
What the times are anchored to
Industries do not publish approval timelines. Products do, lender by lender. These are the published figures the table leans on:
| Product | Published figure | Lender |
|---|---|---|
| Line of credit | "Get a decision in as fast as five minutes" | Bluevine |
| Equipment financing | "Most credit approval requests receive same-day decisions" | Crest Capital |
| Merchant cash advance | Approval "in as fast as 2 hours" | Credibly |
| Online term loan | Funds "as soon as the same day" after approval, before a 10:30 a.m. ET weekday cutoff | OnDeck |
These are best cases from one lender each. Treat them as the fast end of the range, not the middle. SBA-backed loans have no single published timeline; the lender's own process and the loan size set it, and weeks to months is typical.
Why the same loan takes longer in some industries
Lenders decide on cash flow, and each industry's cash flow has a shape. When the shape is steady, a lender can decide quickly. When it is lumpy, the lender asks questions, and each question adds time.
- Healthcare and medical practices. Physicians, dentists and clinics are paid by payers weeks after the work, so monthly collections can swing. A practice with a predictable payer mix and a defined expansion cost is decided faster than one with lumpy collections and an open-ended plan.
- Restaurants and retail. Card and deposit volume is the strongest signal, and it is visible daily. Steady weeks decide fast. Existing advances that already take a share of daily takings slow things down or shrink the offer.
- Trucking and agriculture. The equipment often secures its own financing, which is why equipment decisions can come the same day. A vendor quote and an asset with resale value help. A new trucking authority, or income that arrives at harvest, adds questions.
- Construction, technology and real estate. Income arrives by project, milestone or commission. Signed contracts and recurring fees read as future revenue and speed a decision. One customer covering most of the revenue slows it.
What speeds approval up in any industry
- Send the full application with bank statements in one go. The clock starts there, not at the first form.
- Have a defined amount and use. A quote or a cost beats a range.
- Show the steadiest months you have. Most lenders want recent bank statements; ask how many.
- Disclose existing advances up front. They surface anyway, and late surprises cost days.
- Match the product to the need. An equipment purchase is often faster as equipment financing than as an unsecured loan.
Frequently asked questions
How long does a business loan take for a medical or dental practice?
Online term loans and lines of credit typically decide within hours to a few days of a full application. SBA-backed practice loans usually take weeks to months. What slows a practice down is uneven collections while payers reimburse, and an expansion plan without a defined cost.
Which industry gets approved fastest?
No industry is fast or slow on its own. Businesses with steady daily deposits, such as restaurants and retail, and businesses buying equipment that secures the loan, such as trucking and agriculture, are often decided fastest, because the lender has the least to ask about.
Why does my industry affect loan approval?
Lenders decide on cash flow, and industries have different cash flow shapes. Lumpy income, seasonal income or one dominant customer means more questions before a decision.
Is equipment financing faster than a business loan?
Often, yes. One equipment lender publishes that most requests receive same-day decisions, because the equipment is the collateral and there is no separate property to appraise.
When does the approval clock start?
At the full application, with bank statements, sent to the lender. A first form or a matching questionnaire does not start it.
See which funding partners are ready to fund a business like yours at TopFunders.ai. Free to use, and checking your options doesn't affect your credit.