In This Article
Unsecured business loans are approved faster than secured ones, usually by weeks. An unsecured online loan can fund in 1 to 4 days because there is no collateral to appraise. A secured loan adds appraisal, title search, UCC filing, and legal documentation, pushing real-estate-secured loans to 6 to 12 weeks. The one exception is equipment financing, which closes in 3 to 10 days.
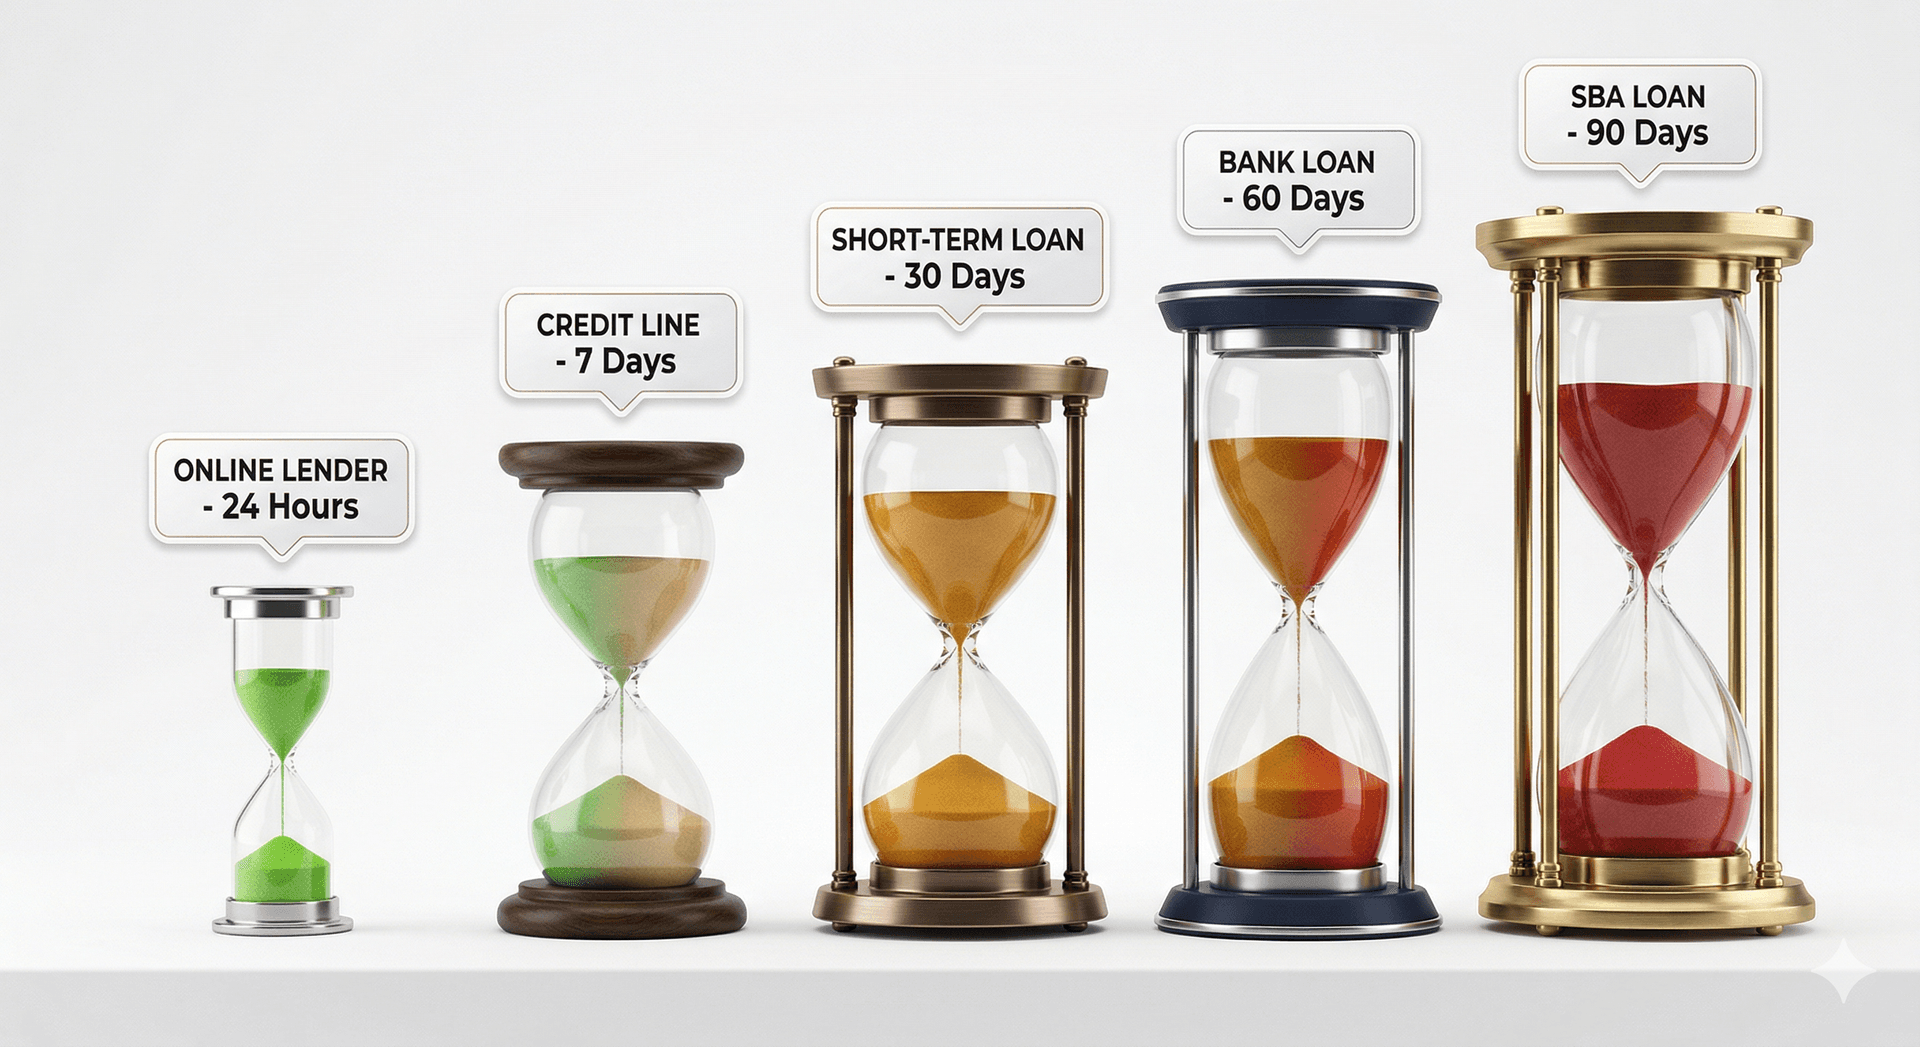
Quick answer: Unsecured wins on speed. Unsecured online loans: 1 to 4 days. Unsecured bank loans: 2 to 4 weeks. Secured equipment loans: 3 to 10 days. Secured bank loans: 3 to 6 weeks. SBA loans secured by real estate: 45 to 90 days. Collateral verification is what adds the time.
That is the speed answer, and it is where most comparisons stop. Speed is rarely what should decide it.
29.0% of the businesses that come to us are borrowing to buy equipment, a larger share than debt consolidation, business acquisition and property combined. In trucking it is 46.3%. For every one of those businesses the secured-versus-unsecured question is not "what can I pledge?" It is "the machine I am buying can secure its own loan, so what does that change?"
It changes a lot: usually the price, often the amount, sometimes whether you qualify at all. This guide covers the approval timeline for both loan types, and then the part most comparisons skip: when the slower option is the right one.
Use-of-funds figures are self-reported by more than 1,000 businesses that have used TopFunders.ai.
Secured vs unsecured: the key difference
A secured business loan requires collateral, a physical asset such as real estate, equipment, or inventory the lender can claim if you default. Because the lender has a tangible safety net, rates are lower and amounts higher.
An unsecured business loan requires no collateral. Approval is based on your business's financial profile: credit score, revenue, cash flow, and time in business. The lender takes more risk, so rates are higher, but the process is faster.
That speed difference is the critical point. Collateral has to be identified, appraised, verified, and legally documented. Every one of those steps adds time.
Who should be looking at secured borrowing?
If what you are buying has resale value, secured borrowing is probably your cheapest route, and the asset securing the loan is the thing you were buying anyway. That is a materially different position from pledging property you already own, and it applies to more borrowers than the framing usually assumes.
Equipment is one of the main reasons businesses come to us looking for funding. Most articles on business lending are written as though working capital were the default. For the equipment buyer, three things follow:
| If you are buying | Then | Because |
|---|---|---|
| A vehicle, machine or system with resale value | The purchase can secure its own financing | The lender's downside is covered by the asset, not by your balance sheet |
| Something that becomes part of the building | It cannot secure anything | Fit-out, wiring and plaster have no resale value to recover |
| A mix of both | Split the application | Financing each part on its own terms usually beats one unsecured loan for the lot |
The trade is real: the lender needs to value what it is lending against, and that takes days the unsecured route does not. What you get for the wait is a lower price and, frequently, access at a trading history or credit profile that would not clear an unsecured approval.
Approval time comparison: secured vs unsecured
| Loan type | Collateral | Approval time | Funding time | Total timeline |
|---|---|---|---|---|
| Unsecured online term loan | None | 24 to 48 hrs | 24 to 48 hrs | 1 to 4 days |
| Unsecured line of credit (online) | None | 24 to 72 hrs | 24 to 72 hrs | 2 to 5 days |
| Unsecured bank term loan | None | 1 to 2 weeks | 1 to 2 weeks | 2 to 4 weeks |
| Secured equipment loan | Equipment | 2 to 5 days | 2 to 7 days | 3 to 10 days |
| Secured bank term loan | Real estate/assets | 2 to 4 weeks | 1 to 2 weeks | 3 to 6 weeks |
| SBA 7(a) unsecured (under $50K) | None | 2 to 4 weeks | 1 to 2 weeks | 30 to 45 days |
| SBA 7(a) secured (over $50K) | Assets required | 3 to 6 weeks | 1 to 2 weeks | 45 to 90 days |
| SBA 504 loan | Real estate/equipment | 4 to 8 weeks | 2 to 4 weeks | 60 to 90 days |
| Commercial real estate loan | Property | 4 to 8 weeks | 2 to 4 weeks | 60 to 90 days |
Why unsecured loans are approved faster
The speed advantage comes from one thing: no collateral verification process. A secured loan adds steps that simply do not exist with unsecured lending:
- Asset appraisal. Commercial property appraisal alone takes 1 to 3 weeks. Equipment is typically 2 to 5 business days.
- Title search. Verifying collateral is free of existing liens takes 1 to 2 weeks on real estate.
- UCC filing. Filing a Uniform Commercial Code statement to establish the security interest adds 1 to 3 business days.
- Insurance verification. Collateral must be insured and verified before closing.
- Legal documentation. Security agreements and, for real estate, deed of trust or mortgage documentation add days to weeks of legal review.
An online lender reviewing an unsecured application is looking at bank statements and a credit score, a process that takes hours, not weeks.
Unsecured approval timeline, step by step
The fastest path, an unsecured online loan:
- Hour 0 to 1: 15 to 30 minute online application, bank statements uploaded digitally.
- Hour 1 to 24: Automated underwriting analyzes statements, verifies revenue, checks credit. Fully automated for straightforward applications.
- Hour 24 to 48: Decision and offer with a specific amount, rate, and term. Strong profiles sometimes get decisions in 4 to 8 hours.
- Hour 48 to 72: Funding after you accept and e-sign. Same-day ACH with some lenders; standard ACH 1 to 2 business days.
Total: 1 to 4 days.
Secured approval timeline, step by step
A secured bank term loan collateralized by commercial real estate, the most thorough process:
- Days 1 to 3: Application plus extensive documentation and preliminary collateral information.
- Days 3 to 10: Initial underwriting review, with document requests common.
- Days 7 to 21: Independent collateral appraisal.
- Days 14 to 28: Title search and legal documentation review.
- Days 25 to 42: Credit committee approval and commitment letter.
- Days 35 to 55: Closing, executing legal documents, recording liens, verifying insurance, UCC filings.
- Days 42 to 60+: Funding after closing conditions are satisfied.
Total: 6 to 12 weeks minimum for real-estate-secured loans.
So which should you choose?
Fastest is not the same as best, and the answer depends on one thing:
Choose unsecured when the need is urgent and unplanned. A failure that stops you trading, a deadline that will not move, an opportunity with an expiry date. You are paying for speed, and in that situation speed is worth paying for.
Choose secured when you are buying an asset. The wait is days, not weeks, on equipment financing, and it buys you a lower rate on money you will be repaying for years. If the purchase is planned, and equipment purchases usually are, the calendar is on your side.
Choose secured when unsecured is closed to you. This is the case least often stated. A business that cannot clear an unsecured lender's revenue or credit floor may still finance an asset, because the asset carries the risk the file cannot.
The one place secured competes on speed outright is equipment financing: the equipment is verified via invoice or purchase agreement rather than appraised over weeks, so those loans close in 3 to 10 days. Outside equipment financing, collateral verification adds weeks that cannot be compressed.
When waiting for a secured loan is worth it
- You need a large amount. Unsecured loans top out around $250,000 to $500,000 with most lenders. For $750,000+, secured lending or SBA programs is likely the only path.
- You want the lowest rate. On a $500,000 loan, the secured-vs-unsecured rate difference can save $30,000 to $80,000 in total interest.
- You have a long runway. A planned property purchase or major expansion gives you time to do it properly.
- You are applying for an SBA loan. SBA 7(a) loans over $50,000 typically require collateral when available, with government-backed rates that are hard to match.
How to speed up either loan type
- Have documents ready before applying. 3 to 6 months of bank statements, 2 years of tax returns, a current P&L. For unsecured loans, the full application with bank statements is what makes same-day approval possible: see approval times by product.
- Apply mid-week. Tuesday through Thursday tends to process faster than Monday or Friday.
- Respond to lender requests the same day. Every hour of delay adds to the timeline.
- Match to the right lender first. Applying to a lender whose criteria do not fit means rejection and wasted time. A matching service like TopFunders.ai checks your profile against 30+ vetted lenders and introduces you to the partners ready to make an offer on a business like yours, with no SSN or Tax ID to match and no credit score impact.
- For secured loans, order the appraisal early. Appraisal is often the longest single step; starting it early compresses the total timeline.
Frequently Asked Questions
How long does it take to get an unsecured business loan?
Online lenders can approve and fund unsecured business loans in 24 to 72 hours. Unsecured bank loans take 2 to 4 weeks. The fastest option, from specialized online lenders, can fund the same day for strong profiles.
How long does it take to get a secured business loan?
Equipment loans close in 3 to 10 days. Secured bank term loans take 3 to 6 weeks. SBA loans secured by real estate take 45 to 90 days.
Why does collateral slow down loan approval?
Collateral adds mandatory steps that cannot be skipped: appraisal, title search, UCC filing, insurance verification, and expanded legal documentation. Each depends on third parties (appraisers, title companies, attorneys) on their own schedules.
Can a secured business loan be faster than an unsecured one?
In rare cases, yes, specifically equipment financing. Equipment is easy to verify via purchase invoice and has a clear market value, so equipment loans can close in 3 to 7 days. For all other secured types, unsecured is faster.
What is the fastest type of business loan available?
Merchant cash advances fund fastest, sometimes same day. Among traditional products, unsecured online term loans and lines of credit are fastest, typically 24 to 72 hours. AI-powered lenders sometimes decide in under 4 hours.
Does applying for a secured or unsecured loan affect my credit score?
Both involve a hard inquiry when you formally apply, which can temporarily lower your score by 2 to 5 points. A no-credit-check matching service like TopFunders.ai lets you identify the right loan type and lender before any credit inquiry, with no SSN or Tax ID required.
Is it harder to qualify for a secured or unsecured business loan?
It depends on what you have. If you own significant assets, a secured loan can be easier to qualify for, the collateral reduces the lender's risk and offsets weaker credit or revenue. Unsecured loans rely entirely on your financial profile.
Should I use equipment financing or a general business loan to buy a machine?
Equipment financing, in most cases. The machine secures the loan, which usually means a lower rate and more flexibility on trading history than an unsecured loan for the same amount. Equipment is one of the most common reasons businesses come to us for funding.
Can I get secured financing if my credit is weak?
Often, yes, and this is the main argument for it. Secured lending shifts risk onto the asset, so a file that would not clear an unsecured lender's credit or revenue floor can still finance a purchase with resale value. The asset has to be worth valuing, and the lender takes time to value it.
The bottom line
Unsecured funds faster; secured costs less. The choice is not really about speed at all. It is about whether what you are borrowing for can carry the loan.
For the 29.0% of businesses coming to us to buy equipment, it can, and the days spent valuing the asset are the cheapest days in the process. For an urgent gap with nothing to pledge, unsecured is not a compromise, it is the correct product. Before applying to either, check which partners fit, for both types, in minutes, at no cost and with no credit score impact.
Find the loan type and lender that fit your profile at TopFunders.ai. Matched to the partners ready to fund a business like yours, with no SSN or Tax ID required and no credit score impact.